Housing market disaster brewing according to ‘Big Short’ investor

Housing market disaster brewing according to ‘Big Short’ investor

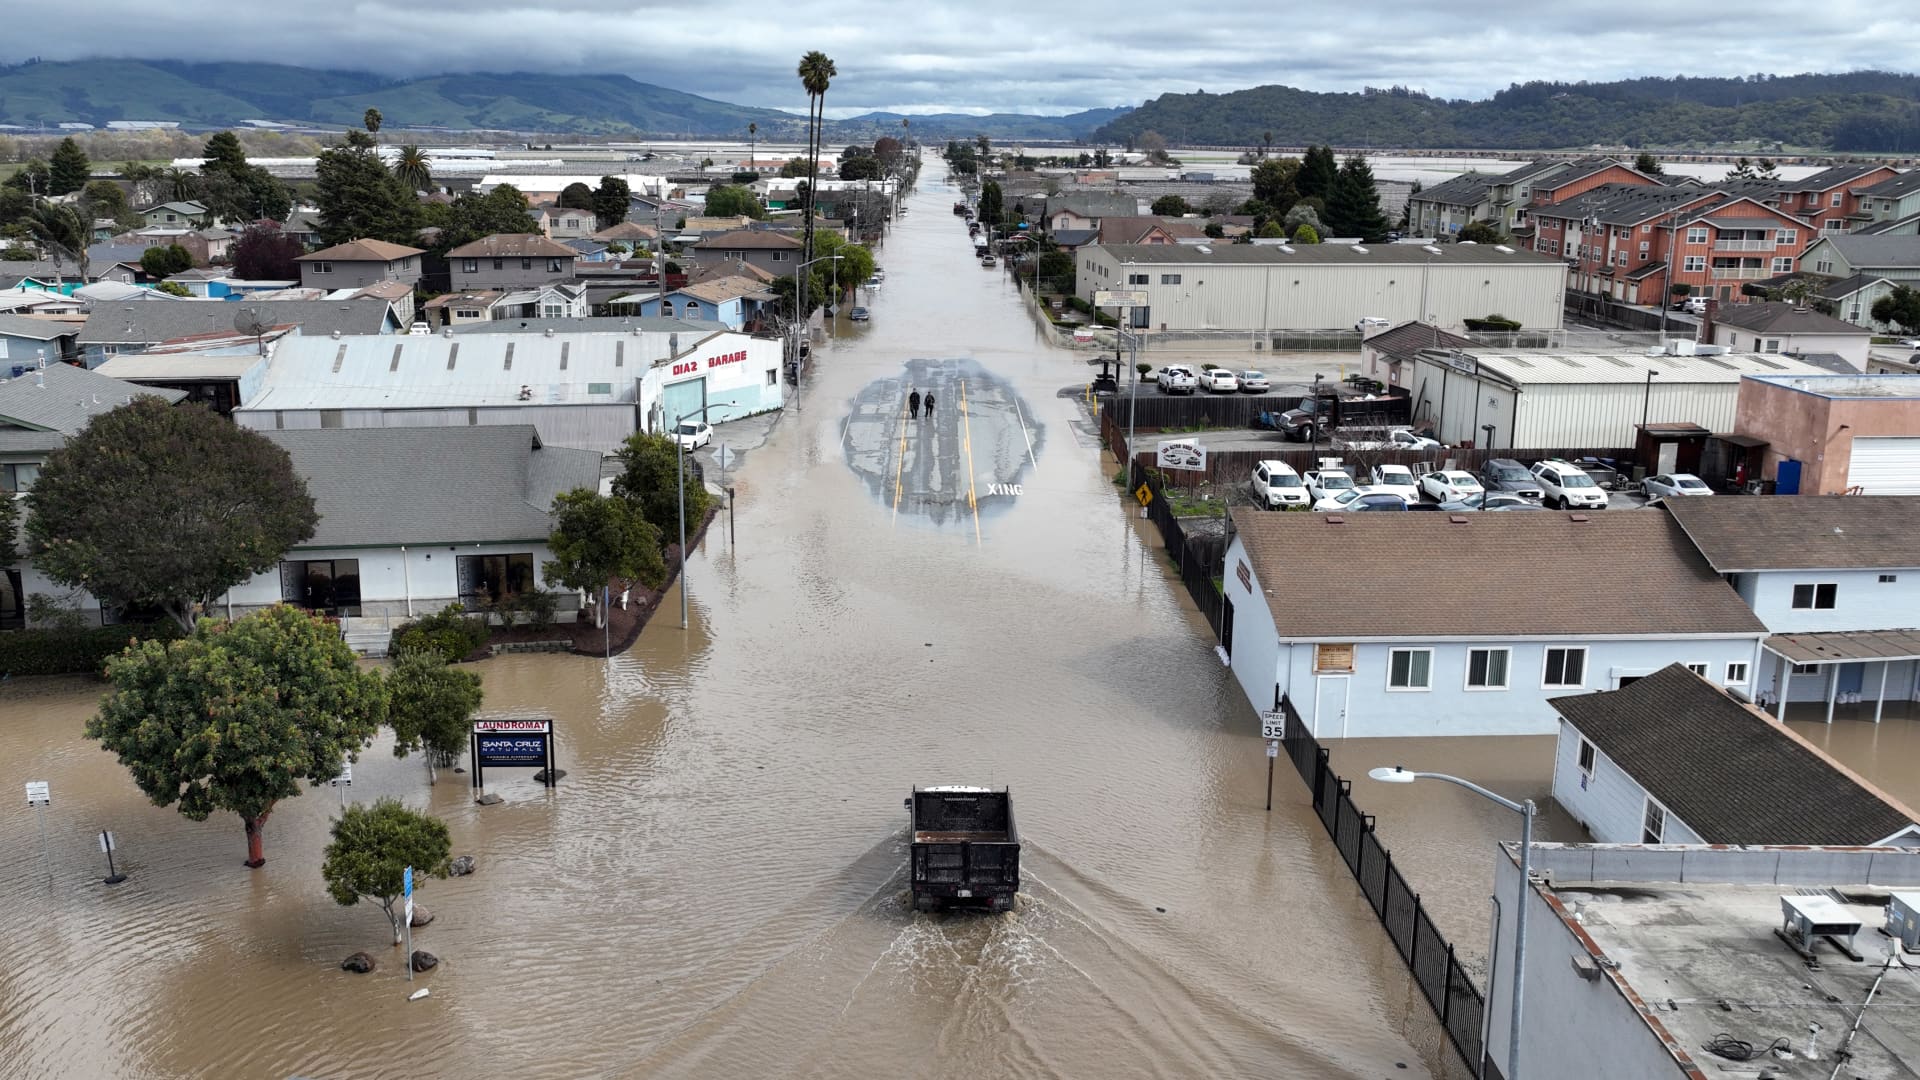
An aerial perspective demonstrates a flooded neighborhood in the unincorporated neighborhood of Pajaro in Watsonville, California, on March 11, 2023.

Josh Edelson | Afp | Getty Images

Extra than a 10 years right after a U.S. property finance loan meltdown threatened to destroy the global economic technique, a “Huge Quick” investor after again sees fiscal disaster brewing in the genuine estate market.

Dave Burt, CEO of investment analysis company DeltaTerra Money which aims to assistance shoppers take care of climate chance, was 1 of the handful of skeptics who regarded the housing current market was on the brink of collapse in 2007.

He assisted two of the protagonists of Michael Lewis’ bestselling e book “The Massive Small” wager versus the mortgage marketplace in the guide-up to the 2008 worldwide financial crisis. As it turned out, they have been proper and were believed to have manufactured millions.

Now, Burt thinks an ignored local weather hazard could see heritage repeating alone.

“I am often on the lookout for these big systemic troubles and there is certainly a few causes for that,” Burt told CNBC via videoconference.

“Skillfully, if a thing is mispriced, then as an investor, which has been my work for most of my job, your primary opportunity to incorporate benefit is to establish a thing that is possibly much too low-priced to purchase for your clients or anything that it is much too costly to sell for your consumer,” he reported.

“From a personal point of view, and this is partly based on that professional viewpoint, I’ve found when that goes wrong, how impactful that can be on economies and society and our most susceptible. And I am genuinely thinking by means of the submit-international fiscal crisis interval listed here in the U.S. from 2008 to 2012 in which there was a huge total of human suffering.”

Inevitably, you are going to strike both a regional or countrywide tipping point in which there is heading to be some variety of bubble that bursts.

Jeremy Porter

Head of weather implications at Very first Road Foundation

Burt stated DeltaTerra Capital’s study suggests that 20{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} of U.S. houses have “significant publicity” to a mispricing situation mainly because of flood chance. If understood, he warned the fallout could resemble the remarkable correction seen during the world economic crisis.

“We assume of this repricing situation as it’s possible a quarter of the measurement and magnitude of the [global financial crisis] in mixture, but of class extremely, extremely harming within just all those uncovered communities,” Burt claimed.

His comments arrive at a time when the housing current market is at present encountering a big essential shift due to the fact of increased home finance loan fees and as international central banks maintain up the fight against inflation by mountaineering fascination prices.

In switch, Burt states some cracks are starting up to show up in the phrases of the price of insurance policies. He famous the recovery in Florida from Hurricane Ian was an concern he is seeing intently, significantly for the reason that this storm surge uncovered a flood coverage nightmare for homeowners.

“Will they become chasms this 12 months? I’m not guaranteed,” Burt mentioned. “But an observation of the maximum frequency essential facts on property sales and property inventories implies that points are absolutely going south for these uncovered homes.”

U.S. housing marketplace overvalued?

Even though most traders continue to be skeptical of the impression of climate pitfalls on their portfolios, a the latest examine warned the U.S. housing market could be overvalued by all around $200 billion owing to unpriced flood threats.

The investigation was published in mid-February in the journal Character Weather Alter. Authored by researchers from the Environmental Defense Fund, the 1st Road Basis and the U.S. Federal Reserve, amid other individuals, the analyze modeled property-degree alterations in flood danger throughout the U.S. in excess of the subsequent a few a long time and warned that reduced-cash flow households were being significantly vulnerable to household benefit devaluation.
Cities are largely to blame for climate change. Could they also be part of the solution?

“The largest cause why it matters from our viewpoint is that local climate hazard isn’t remaining priced into the housing market,” Jeremy Porter, head of local weather implications at the Very first Avenue Basis, advised CNBC.

“The fees now or the valuations of houses really don’t get into account the realization of that true flood risk, and which is not taking into account that we have a tremendous quantity of overvaluation hooked up to qualities throughout the region.”

Porter warned that as individuals proceed to lack adequate local climate hazard information and facts when acquiring their properties, a danger persists that homes could appear to eliminate a important proportion of their assets worth right away.

“It is not that farfetched to say that you hit a tipping position,” Porter reported. “It might be community by group. It may well be a larger sized tipping stage that you strike throughout the nation in the authentic estate current market. But eventually, you are likely to strike possibly a regional or nationwide tipping stage exactly where there is likely to be some type of bubble that bursts.”

Aerial pictures exhibit problems on Fort Myers Beach on March 1, 2023, triggered by Hurricane Ian, which produced landfall in late September 2022.

Orlando Sentinel | Tribune Information Services | Getty Images

At current, the analyze stated almost 15 million U.S. qualities encounter a 1{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} once-a-year likelihood of flooding, with expected once-a-year damages to household attributes forecast to exceed $32 billion.

It also warned the increasing frequency and severity of flooding amid the deepening climate crisis could see the amount of U.S. homes uncovered to flooding improve by 11{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} and normal yearly losses leap by at least 26{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} by 2050.

“When you invest in a residence, just one of the most important issues is the price of sustaining that dwelling and I think so several critical selections are built based mostly on that,” Burt claimed.

“Eventually, until people today have good facts about what these local weather-similar expenses are heading to look like, we’re building new problems every single day. I imagine that is seriously the crux of the make a difference.”

Reflecting on the study’s findings, Jesse Gourevitch, a postdoctoral fellow at the Environmental Defense Fund, instructed CNBC that the overvaluation was additional prevalent among the lower-income property house owners.

He added that “if rate deflation were being to take place, this very much has the likely to widen prosperity gaps in the U.S. and exacerbate inequality.”

One more important risk, Gourevitch stated, was probably to be the potentially detrimental outcomes on nearby government tax revenues for the reason that the full for municipalities typically relies closely on assets taxes. “And obtaining that tied to a bodily asset that is uncovered to weather modify I think introduces a ton of risks to the steadiness of that earnings stream,” Gourevitch explained.

‘A humanitarian crisis’

Much from a domestic challenge, Burt stressed that the local weather dangers linked with the U.S. housing sector posed a significant trouble for nations around the world around the globe.

“I consider when you start out thinking about these issues globally, you begin contemplating about the greater implications that really the most uncovered international locations typically come about to be the most impoverished as well,” Burt mentioned.

“It is a lot more of a humanitarian disaster when you get started looking at this through the international lens.”

TOPSHOT – Aerial view shows an region completely ruined by the floods in the Blessem district of Erftstadt, western Germany, on July 16, 2021.

SEBASTIEN BOZON | AFP | Getty Photographs

Munich Re, the world’s largest reinsurance enterprise, observed steep financial losses in 2022 as the climate disaster drove far more severe temperature events, these as Hurricane Ian in the U.S. and apocalyptic flooding in Pakistan. Reinsurance refers to insurance policies for insurance coverage corporations.

It estimated that these losses amounted to $270 billion very last year, of which around $120 billion was coated by insurance policy. The insured decline full proceeds a pattern of substantial losses in latest several years.

“At the finish of the day, somebody has to fork out for these escalating losses,” Ernst Rauch, chief climate and geo scientist at Munich Re, advised CNBC. “No issue irrespective of whether it is insured or not, it is an increasing financial burden.”

1 area of certain concern, Rauch reported, was flash flooding. This refers to a certain style of flooding in which rain falls so quickly that the fundamental ground simply cannot drain it absent rapid plenty of.

He cited the abnormal flooding observed in Germany in 2021 which induced overflowing rivers to devastate towns across western Germany, Belgium, Austria, and parts of the Netherlands, Switzerland and Luxembourg.

Rauch reported the rising frequency of these types of severe local or regional rainfall occasions was however getting underestimated. “It is no subject whether we discuss about a normal property owner in Germany or in other areas of the environment,” he added.

Real-Estate Investing With Little or No Money Down: Investor

Real-Estate Investing With Little or No Money Down: Investor
  • Ana Snider purchased her very first house applying a VA loan.
  • She turned every single property into a cash-flowing asset by leasing them out. 
  • She shares different kinds of mortgage help plans that everyone can use to get began.

Ana Snider claims the American dream is not useless. But sluggish and steady, and just setting up somewhere, wins the race. 

She’s an energetic obligation Navy officer who took an curiosity in authentic estate immediately after renting out the supplemental bedrooms in her key property. 

Before getting her initially house, Snider had been residing in army-foundation housing and required her personal place. So she began on the lookout for her very first property even though preserving up for what she considered would be a essential down payment. 

On the other hand, she was capable to use a VA Mortgage, backed by the Division of Veteran Affairs, for her to start with obtain, which required no dollars down. It landed her a four-bedroom, 3-rest room home for $268,000 in Lemoore, California. Her new monthly property finance loan payment would sum to $1,600, in addition utilities which were about $150 to $200 a month. 

Snider then decided to hire out a few of the bedrooms to her coworkers for $500 each and every, creating $1,500 a month. This left her with a living cost of $100 for the mortgage loan as well as utilities. 

“I realized, oh very well, I acquired this asset for absolutely free and now somebody’s paying my hire,” Snider stated. 

A calendar year later, she went off on deployment and rented out the entire assets to one tenant for $1,750. 

Today, Zillow estimates that the same house is truly worth $365,000. For Snider, that expense grew to become a cash-flowing asset that appreciates in benefit more than time. 

The practical experience made her comprehend that investing in actual estate would be a fantastic way to establish generational wealth. When she returned from her deployment, Snider required to find out much more about this asset course. She commenced listening to the “Bigger Pockets” podcast and genuine estate talks on Clubhouse. But the flood of data from distinctive investors only left her far more bewildered. 

Snider experienced a lot of general information but however wasn’t confident how to truly get begun, what type of property to buy, and even what area would be best. 

She resolved to get her real estate license as a beginning stage, signing up for the study course in April 2020. A year later on, she came across a piece of land in Bremerton, Washington that checked off all her ideal containers. It was a piece of land that had two houses on it for $299,777. 

The primary residence, a 3-bed room, 1-rest room single-family members device, sat in the entrance, alongside the principal highway. The back again house was a one particular-bedroom, a person-rest room device. 

Both homes wanted some rehabbing, which Snider liked. With a tiny do the job, she could increase the property values. The front home was livable but outdated. The back household required a little bit much more function. 

By that issue, she had made provides on other attributes but stored obtaining outbid by potential buyers who ended up providing all dollars. This home had been on the market for six months and the previous buyer’s offer had just fallen as a result of. 

Snider was not ready to get a VA loan for the comprehensive quantity simply because the appraiser would not evaluate the back device as a home and in its place labeled it as a storage unit. So she had to safe a standard bank loan with a 2.99{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} interest fee and a 3{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} down payment. Her down payment was $8,994. Her in general monthly mortgage loan would be $1,647. 

Snider then moved into the key household when she up to date the flooring and did some dry walling on the back again dwelling. The subcontractor who did the do the job put his time in pro bono so Snider only paid for the substance. In exchange, when he was completed, he would lease the principal house for $1,400. 

About two months later on, the subcontractor became her tenant and Snider moved to the back household where by she would spend the subsequent 9 months. A large aspect of her home finance loan was now protected by her new tenant. This left her with a regular payment of $200 to protect the home loan. 

Right after a few months, she required far more house and commenced hunting for a more substantial most important residence so she could also rent out the back again property. 

In May perhaps 2022, she bought her third home. It was a solitary-household, three-bedroom, two-lavatory dwelling that experienced been lately renovated. This property also sat on a massive ton, which would permit her to develop an supplemental house on it in the future. 

The buy selling price was $429,000. Snider turned to the remainder of her VA loan, which protected most of the amount, other than for $11,700. Snider would need to have to include that hole out of pocket. 

By this time, she had her broker license and was equipped to depict herself as the buyer’s agent on the home. As soon as she marketed it to herself, her fee was $7,000 which she set toward the income payment. This remaining her with an out-of-pocket price of $4,700. 

Her mortgage loan on that residence would be $2,300. Snider then rented out one particular of the rooms for $1,350. 

Entirely, the a few homes Snider now owns insert up to a total price of $1.1 million, in accordance to Zestimate. The complete money she paid out up entrance on all three additional up to just below $14,000. 

How to get started with little to no cash down

If you come about to have access to a VA loan, it can be a wonderful choice for the reason that it isn’t going to call for a downpayment and you never want to get mortgage insurance. Every county has a cap on the financial loan total. But if you purchase home that’s under that cap and however have some loan dollars in leftovers, you can use it for supplemental attributes. 

To be qualified, you or your spouse must satisfy a several specifications set by the Department of Veterans Affairs, and the lender’s credit and income necessities. You will also need a letter of eligibility from Veterans Affairs. 

Whilst Snider was equipped to accessibility a VA loan for two of her houses, she famous that if you aren’t in the army, there are several other financing options you can turn to that would also allow for you to get started investing with minimal dollars down. 

The first just one is a Federal Housing Administration bank loan (FHA). This is a authorities-insured house loan that calls for a reduce down payment. You can put down as small as 3.5{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} without having acquiring strike with a bigger curiosity fee. You can also stay clear of the added cost of home finance loan insurance plan, which standard loans involve if your down payment is down below 20{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}.

If you are using advantage of an FHA bank loan, you are going to need to shift into the property for at minimum a calendar year. Snider recommends having benefit of this head commence by on the lookout for properties with multi-units. This permits you to rent the other units to address your property finance loan payments. You can get a home that has up to four models, or a fourplex, and even now have it categorized as a residential bank loan. If Snider were to start off around, she told Insider her to start with property would be at least be a duplex. 

There are also a large amount of 1st-time residence buyer down payment incentives presented at the state amount. The phrases of these packages vary from condition to state but a straightforward Google search will pull up the selections out there for your spot. You can combine the condition guidance systems with an FHA or regular financial loan. 

A USDA mortgage is a further possibility. This is a form of home loan supplied for homes in some rural regions by the United States Office of Agriculture, Rural Growth. These loans can supply up to 100{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} of the expected financing to capable potential buyers, including the closing expenditures. 

Having said that, obtaining permitted has constraints which include that it need to be a one-family members residence and be in particular geographic locations. 

Last but not least, innovative funding is another choice, which just means alternate means of acquiring a loan. A person primary route that buyers can request for is to have the vendor finance the financial loan. This simply just means as an alternative of turning to a lender, you can sign a agreement with the vendor and shell out every month as although it were being a lease payment. There are quite a few factors why a vendor may agree to these types of an arrangement, like the have to have to get out of a property finance loan they cannot afford or just wanting to offload the house speedily. 

Regardless of how you get commenced, many solutions could be explored, Snider noted. You just have to get started somewhere. 

“I only moved to the United States in 2001 and the American Desire is not lifeless. You just have to go after it because there are millionaires currently being built in real estate every working day,” Snider said. “A good deal of them started out with just an FHA financial loan and downpayment support.” 

Why This Billionaire Investor Is Aggressively Buying Income-Producing Properties

Why This Billionaire Investor Is Aggressively Buying Income-Producing Properties

If you possess a property or have been intrigued in acquiring a person, you are informed of the sizeable U.S. household actual estate downturn. Sales figures are dropping to their most affordable costs given that 2020, but interest fees keep on to rise to close to 6.5{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}. This state of affairs doesn’t imply traders should seem to yet another possibility considered as significantly less volatile.

Just take actual estate investment trusts (REITs), for instance. REITs are not just a platform for investing in residential serious estate, providing properties this kind of as retail areas, significant malls, lodges, condominium properties, workplace room and hospitals. And although property selling prices keep on to be significant, other true estate types are not as overvalued, most likely shielding buyers from the threat of steep cost declines.

Buyers have not given up on the residential marketplace, utilizing funding solutions to just take advantage of small housing inventory and turning homes into rentals. This strategy contributes to the superior housing selling prices seen in the previous couple of years.

In accordance to house intelligence knowledge firm CoreLogic, the trader share of solitary-relatives properties offered in the to start with quarter of 2022 achieved 28{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}, 11{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} more than the same period of time in 2021. Its facts also showed that investors with a thousand or more residences acquired 3{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} of homes in 2021 and so much in 2022, compared to 1{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} in past several years.

Big real estate gamers like Redfin Corp. and Offerpad Alternatives Inc. also acquired homes on a massive scale. Zillow Group Inc. fell on its experience in this endeavor, alienating true estate brokers who stopped advertising with a company they believed was competing in opposition to them. “The offer lack is also an benefit for landlords,” Redfin economist Sheharyar Bokhari said. “Many men and women who can not uncover a home to obtain are compelled to lease alternatively.”

Serious estate billionaire, creator and profits coach Grant Cardone sees opportunity in the recent current market.

“I feel we are getting into the Best authentic estate market prospect considering the fact that 2008. With the Fed increasing curiosity prices, it has sidelined house consumers, which indicates charges are likely to pull again. If you are an close-person on the lookout to enter the housing market place, now is a terrific time to invest in a dwelling more cost-effective than it would have been at the starting of the yr. You need to appear for persons who late previous 12 months or early this year had been hoping to make a rapid flip and had an adjustable mortgage. They are waking up devoid of a current market to promote into and payment on their personal loan that is doubling,” he reported. “Also search for institutions who have previously created a great deal of their portfolios down and will bring a ton of item/inventory to the marketplace in the previous quarter of this year.”

Cardone, the previous Undercover Billionaire on the Discovery Network and a CEO or lover with seven privately held providers, set a stamp on his perception that buyers have to have not operate from serious estate investing by saying, “I am an aggressive buyer via the stop of the 12 months and next yr of revenue-manufacturing genuine estate.”

Of class, not anyone has the money on hand to obtain up discounted houses. A expanding selection of investors are turning to additional passive options like Cardone’s managed actual estate cash as a result of Cardone Funds, which has currently raised approximately $1 billion from approximately 12,000 accredited and non-accredited buyers and features a portfolio comprised of approximately 12,000 multifamily units and over 235,000 sq. toes of business business area.

Some buyers are even receiving in on the market place with as little as $100 as a result of the Jeff Bezos-backed true estate investing system that sells shares of single-family rentals. The enterprise has presently funded 203 qualities with a value of much more than $75 million.

Extra on Real Estate from Benzinga

Graphic by leolintang on Shutterstock

First tale located listed here.

Really don’t skip true-time alerts on your shares – join Benzinga Professional for absolutely free! Try the instrument that will aid you devote smarter, a lot quicker, and greater.

© 2022 Benzinga.com. Benzinga does not supply financial commitment assistance. All rights reserved.